Five Common Mistakes Bluebell Homeowners Make When Filing Storm Damage Claims
The small, avoidable decisions that delay or shrink storm damage claims in Bluebell — and the simple habits that keep yours on track.
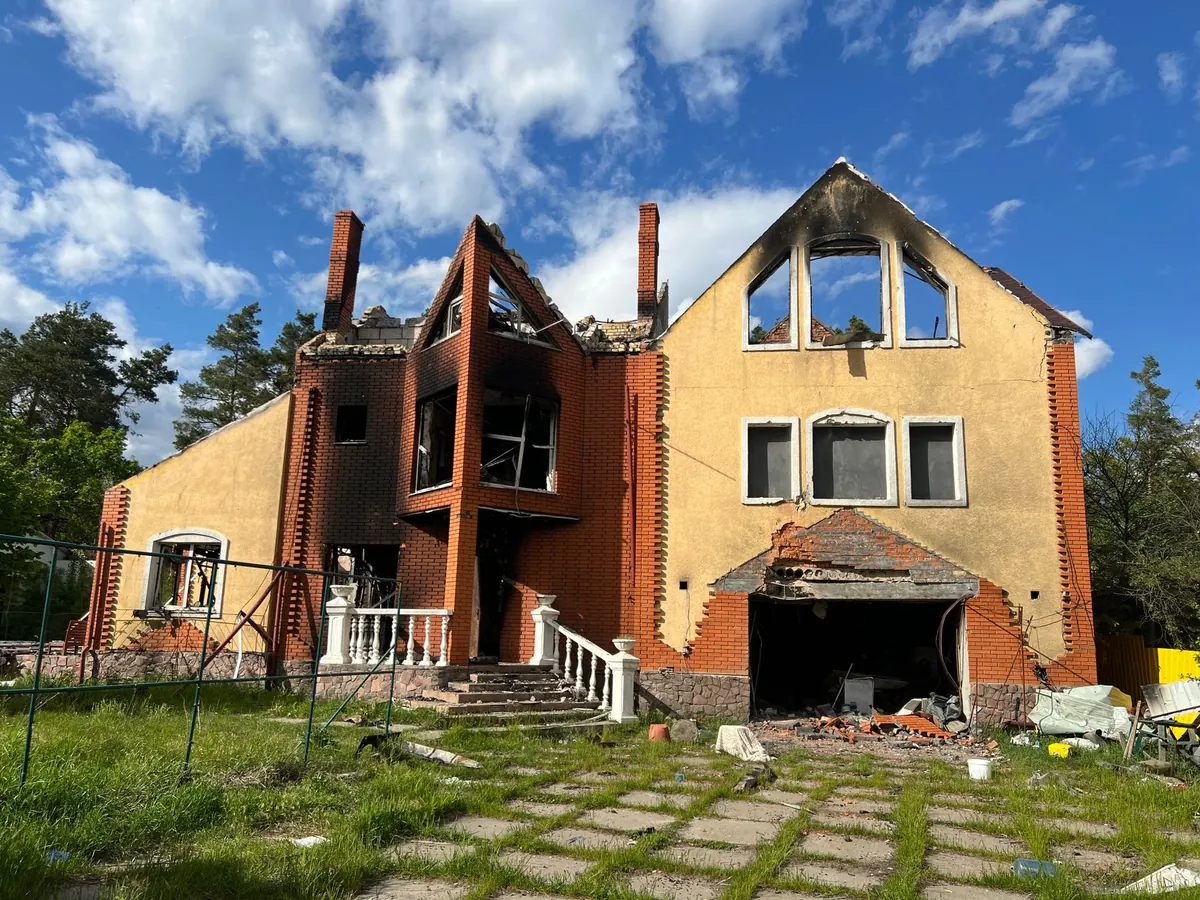
Storms in Bluebell tend to arrive fast. A line of storms rolls through, the power flickers, and by morning there is a limb on the garage and water spreading across the basement floor. What happens in the next few days usually decides how the claim goes — not the storm itself.
Most claims that get delayed, reduced, or denied are not ruined by bad luck. They are ruined by small, avoidable decisions made in the first week. Here are the mistakes that come up most often, and what to do instead.
Mistake one: Cleaning up before you take pictures
This is the most common one, and the easiest to avoid. Your instinct is to drag the branch off the roof and get the wet carpet out of the house. Take the photos first. Then clean up.
What adjusters actually need to see:
- wide shots of each damaged area, showing where it sits in the house or yard
- close-ups of the damage itself
- something for scale — a tape measure, a shoe, your hand
- the same area from two or three angles, from outside and inside if water came through
- a slow video walkthrough while you narrate what you are looking at
Plain, unposed photos are more useful than careful ones. Do not throw away damaged items — the ruined carpet, the soaked drywall pieces — until the adjuster has seen them or told you it is fine to dispose of them. If you have to make a temporary repair to stop further damage, photograph the broken thing first and keep the receipt for the tarp or plywood.
Mistake two: Guessing at your policy instead of reading it
Two neighbors, same storm, same street, very different checks. That is not favoritism; that is policy language.
Read the declarations page and the sections on wind, hail, water, and outbuildings before you call anyone. A few things that trip people up:
- Many policies carry a separate, percentage-based deductible for wind and hail, which can be far higher than the flat deductible printed on the front page.
- Water that backs up through a sump pump or floor drain is often excluded unless you bought a specific endorsement.
- Flood damage — rising water from outside — is generally not covered by a standard homeowners policy at all, and usually needs its own policy.
- Detached garages, sheds, fences, and pools typically have their own limits.
If the wording is confusing, ask your agent to explain it in writing. For a large or contested claim, a licensed public adjuster or an attorney who handles insurance disputes may be worth a conversation. Where money and legal rights are involved, get proper professional advice rather than relying on a neighbor's story.
Mistake three: Treating a contractor's estimate as the final word
A contractor's estimate is your repair plan. It is not the insurer's valuation, and the two rarely match on the first pass. The gap usually sits in the scope: whether the decking under the shingles gets replaced, whether code-required upgrades are included, how much siding is genuinely affected.
Get at least two written, itemized estimates. Itemized means line by line — labor, materials, tear-out, disposal — not a single lump figure on a business card.
Red flags in a contractor pitch
- Anyone who offers to "waive your deductible." In most places that is not permitted, and it is a signal to walk away.
- Contracts that assign your claim rights to the contractor, which can leave you out of the loop on your own claim.
- Large cash deposits demanded up front.
- Pressure to sign the same day, before you have read anything.
Ask for a written scope, a timeline, and a license number. If a contractor will not put things in writing, that tells you something.
Mistake four: Missing deadlines nobody reminded you about
Policies require prompt notice of a loss. "Prompt" is not an invitation to wait until you have had three contractor visits. Report the damage as soon as you reasonably can, even without the full picture — you can supplement a claim later.
After that, keep track of dates. There is often a deadline for submitting a sworn proof of loss, a window for responding to requests for information, and time limits on appeals if a claim is denied. Contractors have their own deadlines for preserving lien rights, which can affect what you ultimately owe.
The fix is simple. Start a claim log, in a notebook or a document, and add an entry whenever something happens: the date you called and who you spoke to, the claim number and the adjuster's name, what was promised and by when, when the contractor came out, what you sent and when. Put anything important in writing, by email if you can. A phone call is easy to misremember; an email is not.
Mistake five: Winging the conversation with the adjuster
Be there for the inspection. Walk the property with the adjuster and point things out room by room. Adjusters are busy and often work from the outside in. If you do not mention the hairline crack in the ceiling of the back bedroom, it may not make the report.
Two habits matter more than anything else here. First, do not speculate about cause. "The limb came down in the wind" is fine. "I think the roof was already failing" is not — that is you doing the insurer's job of finding an exclusion. Second, do not pad the claim. Inflating damage is the fastest way to turn a routine claim into a credibility problem.
After the visit, ask for the adjuster's report and the scope of work. Read it against your own list. If something you showed them is missing, say so in writing, with the photos that prove it. If you accept an offer, make sure you understand what it covers and what it does not before you sign a settlement.
Mistake six: Forgetting the costs that are not obvious
The roof gets all the attention, but claims lose money in the small lines. Keep every receipt for tarps and plywood, a hotel or rental if the house is unusable, meals out while the kitchen is torn up, the contents of the chest freezer, tree removal, and the cost of moving furniture to safety. Many policies cover at least some of this, often through additional living expenses or a specific limit for debris removal — but only if you can show the receipts.
Also, tell the insurer before you make permanent repairs. Temporary work to prevent further damage is expected. Replacing the whole roof before anyone has seen it is a different story, and it can complicate the claim.
Before you file: a five-minute checklist
- Photograph and video everything, inside and out, before you clean up.
- Read the wind, hail, water, and deductible sections of your policy.
- Report the loss promptly and write down the claim number.
- Get two itemized contractor estimates, and never sign on the spot.
- Keep a dated log of every call, visit, and email.
- Save every receipt, including the small ones.
Storms here are a when, not an if. The homeowners who come out of them with a fair settlement are usually not the ones who know the most about roofing or insurance law. They are the ones who took ten minutes for photos and kept a folder. Do the boring part early, and the rest of the claim tends to go where it should.
Photo: Yevhen Sukhenko / Pexels